Dakar (AFP) – The International Monetary Fund announced an agreement with Senegal on Tuesday for a new $2.2-billion loan programme, after a prior deal was suspended following the discovery of previously unreported debt. The announcement comes nearly two years after Senegal’s current government, which rose to power on an opposition electoral victory, accused the former administration of ex-president Macky Sall (2012-2024) of having concealed the true extent of the west African country’s worrisome budgetary situation.
As a result, the IMF suspended a $1.8-billion aid programme it had agreed upon in 2023, pending further information and commitments from new President Bassirou Diomaye Faye’s government. The new 36-month arrangement announced Tuesday is meant to support Senegal’s “economic and financial reform program for the 2026–2029 period”. But given past underreporting, it will also require “decisive corrective measures to support the authorities’ request for a waiver regarding the misreporting of data”, the IMF said in a statement. The staff-level agreement will still need to be approved by the IMF’s executive board.
Finance Minister Cheikh Diba told journalists he was “pleased” to announce that Senegal and the IMF had “reached a technical agreement that paves the way for financing prospects”. After several IMF visits to Senegal to examine the country’s financial situation, the IMF and the government began negotiations in mid-October for a new aid programme. Mercedes Vera Martin, division chief at the IMF African Department, told AFP in an interview Tuesday that “since the misreporting was identified, the authorities have taken efforts to improve the transparency”. “That includes several audits” and they have also reconciled their “historical data, incorporating the findings of the debt,” she said.
The IMF said it would additionally require “receipt of the necessary financing assurances from Senegal’s partners”. With a total public-sector debt estimated at 132 percent of GDP at the end of 2024, Senegal is one of the most indebted countries in sub-Saharan Africa. However, its overall fiscal deficit narrowed sharply from 13.4 percent of GDP in 2024 to 6.4 percent of GDP in 2025, mostly driven by spending rationalisation, the IMF said in June. Senegal has been able to continue financing itself largely through regional financial markets but this comes at higher costs than loans from international financial institutions, development banks, or governments.
A simmering political feud between Faye and his then prime minister, Ousmane Sonko, came to a head earlier this year over a variety of topics, including the IMF programme. Although the president sacked Sonko in May, Sonko was afterwards elected speaker of the National Assembly — a role that could complicate Faye’s ability to usher in IMF reforms. While Faye prefers a more conciliatory approach with the IMF, Sonko has rejected any debt restructuring, calling any such move a “disgrace” for the country.
Asked whether the deal calls for restructuring, Martin, who led the IMF’s mission to Dakar from August 19 to September 1, said it included “debt treatment”. “It’s a sovereign decision. The authorities have a debt treatment plan that will allow us to move forward in our engagement”, Martin said. Finance Minister Diba told journalists that “the debt treatment plan is not a restructuring in the traditional sense”. “It is an initiative by Senegal to address its debt in a way that accounts for its specific characteristics”, he said. Calling for “transparency” in a Facebook post late Tuesday, Sonko demanded further details, including what “debt treatment” would entail. And he vowed that any commitments would ultimately be debated in the National Assembly, where his Pastef party holds power, when the measures end up in forthcoming finance legislation.
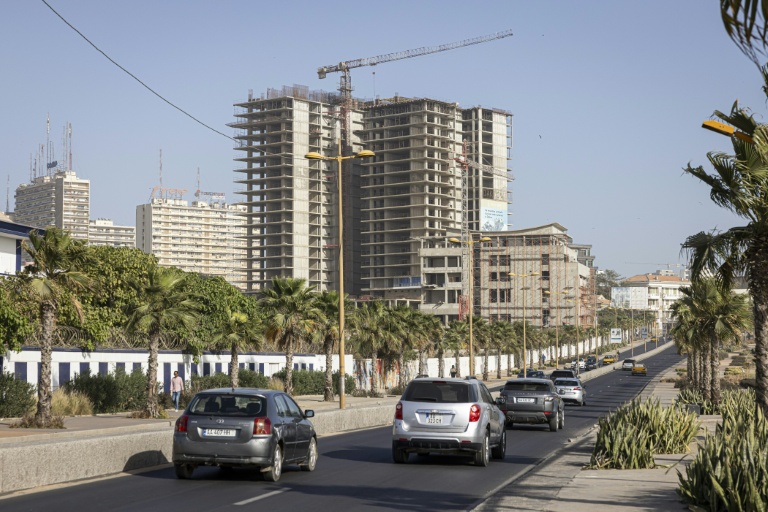
In the latest downgrade by a ratings agency, Moody’s last week cut Senegal’s long-term foreign-currency debt rating to Caa2 from Caa1, mid-negotiations with the IMF. That said, “the Senegalese economy has remained resilient, recording 6.7 percent growth in 2025 driven by the first full year of oil production, although non-hydrocarbon GDP growth slowed to 2.2 percent”, Martin said in the IMF statement. Senegal launched production at its first offshore oil field in 2024.
© 2024 AFP